The shortest lease term isn’t automatically the simplest choice. A 12 month credit card terminal lease limits the length of the equipment commitment, but whether it fits depends on more than the number of months. Compare the equipment, payment obligations, and lease-end option before deciding.
Executech Lease Group (ELG) offers credit-card terminal and point-of-sale (POS) equipment leases with terms from 12 to 60 months. Its FMV and lease-to-own options have different end-of-term structures: the FMV option ends with about a 10% buyout, while lease-to-own ends with a $1 buyout. The term alone won’t tell you which structure applies.
This guide explains how a 12-month term compares with longer commitments, when it may align with your equipment plans, and what to review in a written proposal. Use the payment schedule, equipment details, and lease-end terms to assess the commitment as a whole, rather than choosing based on duration alone.
Key Takeaways
- A 12 month credit card terminal lease covers an equipment commitment, not payment processing or merchant-account services.
- Compare 12-, 24-, 36-, 48-, and 60-month terms alongside the lease-end structure of the selected program.
- Review the written proposal for the specified equipment, term, program type, payment obligations, and lease-end provisions.
- Match the proposal to your business’s equipment requirements and expected use before choosing a lease structure.
- ELG provides credit decisions in 1-2 business hours. This refers to decision timing only.
What Does a 12-Month Credit Card Terminal Lease Actually Commit You To?
A 12 month credit card terminal lease is an agreement to lease terminal equipment for a 12-month term. That describes the equipment commitment and its duration, but not the payment schedule, the program’s end-of-term provisions, or any separate arrangements for accepting payments.
What equipment and agreement does the term refer to?
The term refers to a lease for a credit-card terminal or related payment equipment. The written agreement should identify the equipment covered. “12-month” describes the lease period, not the length of a processor contract or merchant-account arrangement.
Equipment leasing and payment services are separate. A lease covers equipment under its written terms; payment processing and a merchant account involve separate services and agreements. ELG leases equipment. It doesn’t process payments or supply merchant accounts. The equipment lease therefore doesn’t, by itself, define your obligations to a payment processor or merchant-services provider.
Why does the term alone not describe the full commitment?
Two proposals with the same term can still have different program structures and written obligations. Look beyond duration: the agreement sets out the payment obligation and the program-specific provisions that apply during and at the end of the lease.
Review the written proposal for these details:
- Equipment covered: Identify the terminal equipment named in the agreement and compare it with the equipment your business needs.
- Payment terms: Find the stated payment schedule and obligations for the full term.
- Program and lease end: Check which program applies and read its written end-of-term provisions.
ELG offers no-money-down equipment leasing. “No-money-down” describes the down payment, not the total cost or obligation. It doesn’t mean the equipment is free, and it doesn’t replace the payment terms in the agreement. Read those terms alongside the lease period when comparing proposals.
Keep the distinction clear: the lease term tells you how long the equipment agreement runs, while the written agreement explains the financial and program-specific commitment. Start by checking whether that commitment aligns with the equipment your business needs and the obligations you’re prepared to take on.
How ELG’s 12-Month Terminal Lease Options Are Structured
ELG’s credit-card terminal leasing programs include fair market value (FMV) and lease-to-own structures. Each has term choices of 12, 24, 36, 48, and 60 months. This gives you a consistent set of durations to compare, while the selected program determines which lease-end structure applies. A 12-month option is one choice within either program, not a separate promise about what happens after the term.
Compare both dimensions: how long the agreement runs and which program’s terms govern the equipment. ELG’s equipment leasing programs describe the available structures. The written proposal should identify the program and term for your equipment. Evaluate those details together instead of relying on the term label alone.
How do the FMV and lease-to-own options differ?
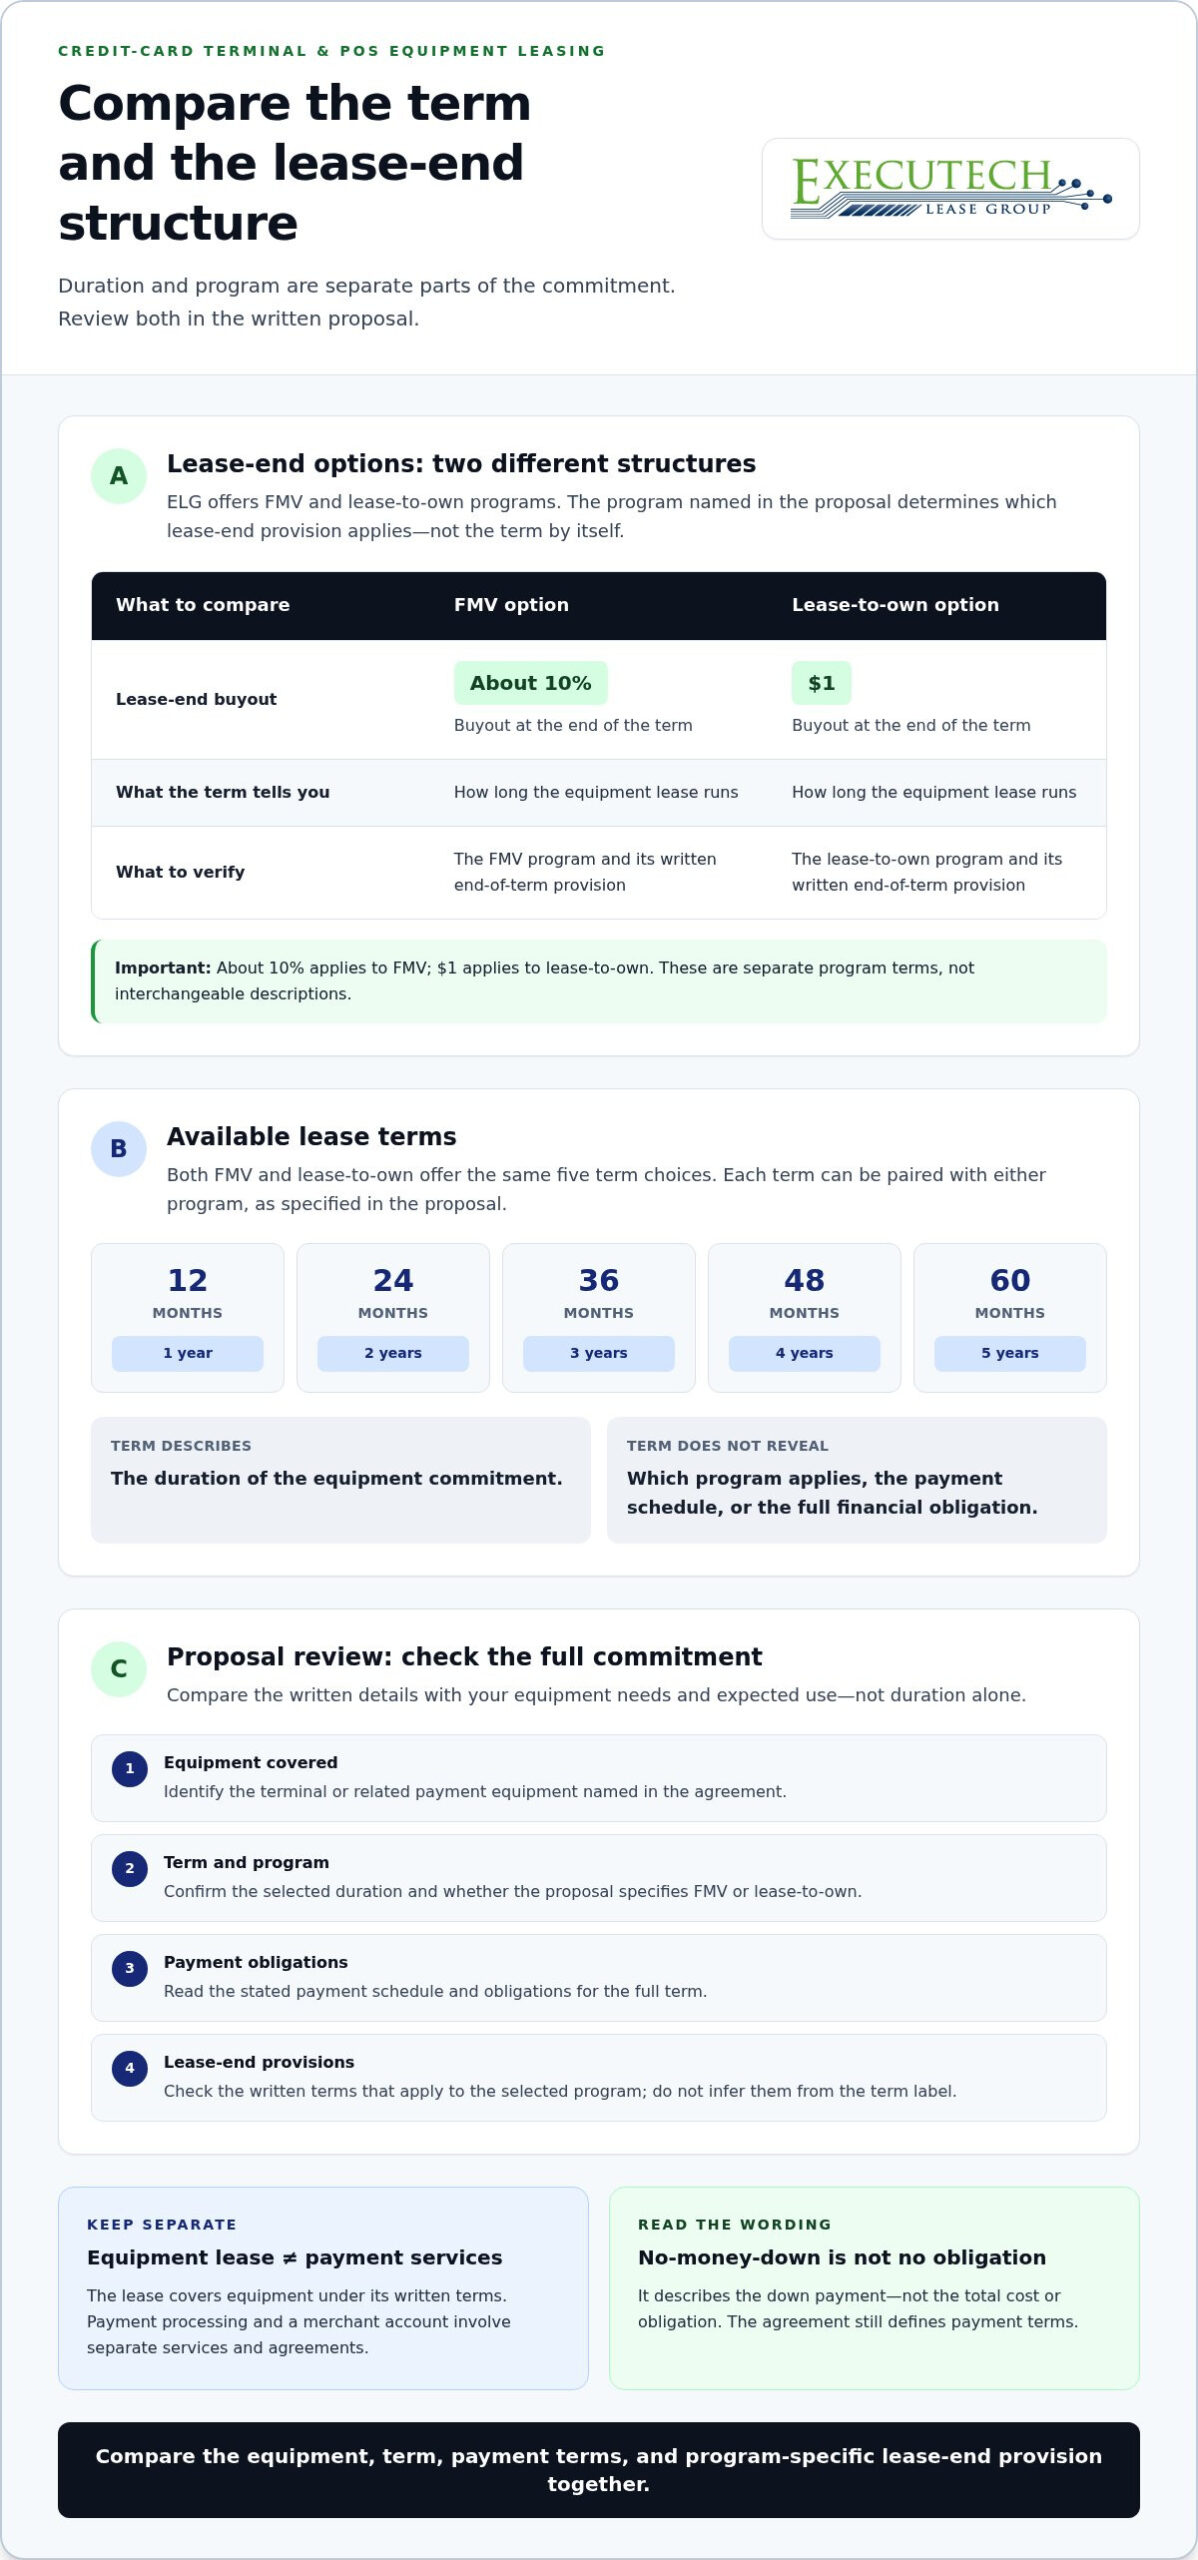
The lease-end distinction is specific. ELG’s FMV option ends with about a 10% buyout. ELG’s lease-to-own option ends with a $1 buyout. These are separate program terms, not interchangeable descriptions of one lease. Don’t assume a buyout structure applies simply because the term is 12 months. Check the program named in the proposal.
For example, if you’re comparing two proposals with the same term, duration alone won’t show whether they share the same lease-end option. Check the program designation and its written buyout provision. About 10% belongs to the FMV option; $1 belongs to lease-to-own.
What does no-money-down mean in this context?
ELG offers no-money-down equipment leasing. That describes the down payment, not the total financial obligation. It doesn’t mean the equipment is free or that no payments are due. The term, program, and payment obligations remain defined by the written agreement.
To compare structures without guessing at costs, focus on what the proposal states. Confirm which equipment and term it covers, identify whether it uses FMV or lease-to-own, and read the applicable payment and lease-end provisions. Don’t infer an FMV buyout calculation or assume the same end-of-term structure applies across programs. The specific written terms matter.
A practical comparison starts with the duration that aligns with your equipment plans, then considers the program’s lease-end structure and written obligations. To explore the available structures, explore ELG’s leasing programs.
12 Months vs. Longer Terminal Lease Terms: What Should You Compare?
ELG offers FMV and lease-to-own term choices of 12, 24, 36, 48, and 60 months. Compare the length of the equipment commitment with the program’s lease-end structure and your operational plans. A shorter term isn’t automatically cheaper or more suitable. The written proposal’s payment terms matter, and duration alone doesn’t reveal total cost.
| Term | Duration | Lease-end structure to compare |
|---|---|---|
| 12 months | One year | FMV or lease-to-own, as stated in the proposal |
| 24 months | Two years | FMV or lease-to-own, as stated in the proposal |
| 36 months | Three years | FMV or lease-to-own, as stated in the proposal |
| 48 months | Four years | FMV or lease-to-own, as stated in the proposal |
| 60 months | Five years | FMV or lease-to-own, as stated in the proposal |
Across these choices, the FMV option ends with about a 10% buyout, while the lease-to-own option ends with a $1 buyout. These provisions belong to their respective programs. The table doesn’t imply a particular payment amount or total cost for any term. Compare the actual proposal rather than assuming a shorter duration means a lower overall commitment.
When might a 12-month term align with equipment plans?
Start with your expected period of use. Consider how the proposed terminal fits current operations and how long you plan to rely on that equipment. A 12-month term may suit a shorter planning horizon; a longer term represents a longer equipment commitment. Neither choice predicts when equipment will need replacement or guarantees an exit before the term ends.
Use your operational plan, rather than assumptions about future upgrades, to frame the comparison. For example, list the equipment functions your business currently needs, then compare that list with the equipment described in the proposal. ELG’s POS equipment leasing programs provide context for comparing equipment lease structures.
Which lease-end option matches the ownership preference?
Separate two questions: how long do you want the agreement to run, and which lease-end structure aligns with your preference? A preference for a shorter term doesn’t, by itself, indicate whether FMV or lease-to-own is the better fit. Compare the program and term together, then read the applicable end-of-term provision in the proposal.
For a 12 month credit card terminal lease, make the comparison concrete: assess your planned equipment use, identify the proposed program, and review its written payment and lease-end terms. This gives you a clearer basis for comparing 12 months with longer choices without treating duration as a stand-in for suitability.
A Practical Checklist for Reviewing a 12-Month Terminal Lease Proposal
A proposal is easier to evaluate when you review it in a consistent order. Compare the document with your business’s actual equipment requirements, then separate the equipment lease from any processor or merchant-account arrangements. ELG’s lease process overview provides context for the steps involved. Use the written proposal as your reference point, not assumptions based on a product description or short summary.
- Identify the equipment. Check which terminal or related payment equipment the proposal describes. Compare it with the equipment your business expects to use and its intended role in your operations.
- Review the use case. Make sure the equipment described corresponds to your actual business requirements. Don’t assume that a terminal will work with every processor or merchant account.
- Separate the agreements. Identify which terms cover equipment leasing and which relate to payment processing or a merchant account. ELG leases equipment; processor and merchant-account obligations are separate.
- Confirm the term. Locate the stated lease duration and compare it with the commitment you intend to make. Read the agreement itself rather than relying on a verbal description or heading.
- Identify the program. Find whether the proposal describes an FMV or lease-to-own structure. The applicable program determines which lease-end provisions to review.
- Read the written obligations. Review the stated payment schedule and applicable lease-end option in the agreement. Base your understanding on its actual language.
Which equipment and payment-system details should you review?
Start with the equipment description and intended use. Does the proposal identify the terminal equipment your business needs? Then keep the payment-system relationship clear. An equipment lease doesn’t establish processor compatibility or replace a separate merchant-account agreement. Treat each arrangement on its own terms, and don’t assume the lease controls obligations to a processor or account provider.
Which written terms deserve a careful read?
Read the term, payment obligations, and lease-end option together. The short label “12-month lease” doesn’t answer every question about the commitment. Don’t infer renewal rules, cancellation rights, or charges that aren’t stated in the agreement. If a provision affects your understanding, rely on the specific written terms rather than filling gaps with assumptions.
Before proceeding, compare the complete proposal with your planned equipment use. Confirm that the named equipment, intended business role, term, program, and written obligations align. That review gives you a practical basis for assessing whether a 12 month credit card terminal lease fits your requirements, while keeping equipment leasing distinct from payment services.
How to Discuss a 12-Month Credit Card Terminal Lease With ELG
A useful discussion starts with three decisions: how long the equipment commitment should run, which leasing program fits your plans, and which lease-end structure aligns with your preference. For a 12 month credit card terminal lease, bring those choices together with your equipment requirements and the written proposal. That keeps the conversation focused on the actual commitment rather than treating term length as the only decision.
ELG leases equipment. It doesn’t process payments or supply merchant accounts. If you’re a merchant, keep your payment processor and merchant-account arrangements separate from the equipment lease. ELG provides credit decisions in 1-2 business hours. That refers to decision timing only, not a promise of approval, funding, equipment delivery, or installation.
What happens after you identify the relevant leasing program?
Once you’ve identified the equipment, preferred term, and program structure, use those details to understand the proposed equipment lease and its written obligations. Keep the review grounded in the proposal. An inquiry or discussion doesn’t guarantee a credit decision or a lease. Decision timing also doesn’t determine what happens next with funding, delivery, or installation.
Before taking a next step, organize the details you’re comparing:
- Equipment: Identify the terminal or point-of-sale (POS) equipment and its intended business use.
- Term: Note the duration you’re evaluating.
- Program: Identify whether the proposal describes FMV or lease-to-own.
- Preference: Be clear about your lease-end and ownership preference.
This gives you a straightforward basis for discussing the equipment lease without confusing it with separate payment services.
Who should use the vendor inquiry next step?
The vendor inquiry is for payment professionals exploring a business relationship with ELG, including independent sales organizations (ISOs), merchant-services providers, agents, and POS dealers. If you’re considering a vendor relationship, describe your business role and the equipment-leasing opportunity you want to discuss. This is a vendor inquiry, not a merchant financing application.
Merchant readers can use the same decision framework to clarify their equipment needs and compare a proposal’s term, program, and lease-end structure. Their processor and merchant-account arrangements remain separate from ELG’s equipment-leasing role. Keep that distinction clear as you review next steps.
Payment professionals considering a vendor relationship can use the Discuss becoming an ELG vendor inquiry to start that conversation.
Make Your Next Equipment Decision With Clarity
Before moving forward, turn your comparison into a short decision record: the business need the terminal must meet, the duration you can plan around, and the proposal language that supports your choice. That gives decision-makers a shared reference point and makes it easier to spot a mismatch between an operational requirement and a lease commitment. A 12 month credit card terminal lease is a term-fit decision, so anchor it in your equipment plan and the written agreement, not simply a preference for the shortest timeline.
Keep payment-services arrangements distinct, and use the lease proposal to understand the specific equipment commitment. If you’re weighing more than one option, compare the same details in each proposal. A consistent review makes the trade-offs easier to discuss and helps your team move forward with a clear rationale.
Payment professionals interested in a vendor relationship can use the inquiry below to begin a focused conversation with ELG.
Discuss becoming an ELG vendor
Move ahead with a clear plan and a documented understanding of the commitment.
Frequently Asked Questions
How much does a 12-month credit card terminal lease cost?
There’s no single cost that applies to every terminal lease. A 12 month credit card terminal lease depends on the equipment and the specific written agreement. Avoid relying on a general estimate when planning your budget. Review the proposal’s payment obligations and applicable lease-end option, then compare them with the equipment your business actually needs. That grounds your decision in the terms presented, not an assumed rate or total.
Can a 12-month terminal lease be the same as a 12-month processor contract?
Not necessarily. A terminal lease covers an equipment arrangement; a processor contract covers payment-processing services. The two may have different terms and obligations. Treat them as separate documents and compare their dates and responsibilities independently. ELG leases equipment and doesn’t process payments or control processor obligations. A lease term ending after one year doesn’t establish when a separate processing arrangement ends.
Does ELG process credit card payments for merchants?
No. ELG provides equipment leasing solutions for credit-card terminals and point-of-sale (POS) systems, but it doesn’t process payments or supply merchant accounts. A merchant’s processing relationship is separate from the equipment lease. Equipment leasing addresses the hardware arrangement, while payment acceptance depends on a separate services relationship.
Does a terminal lease include a hardware warranty?
Don’t assume that every equipment lease includes the same warranty. ELG’s hardware-subscription program includes a hardware warranty for the subscription term, but that applies to the subscription program, not automatically to an equipment lease. If you’re comparing a lease with a subscription, keep the program terms separate. Read the written terms for the specific arrangement to understand what coverage applies.
How quickly does ELG make a credit decision?
ELG provides credit decisions in 1-2 business hours. This describes decision timing only. It doesn’t promise approval, funding, equipment delivery, or installation, and it isn’t a 24/7 decision clock. If you’re planning around a terminal change, treat the credit decision as one distinct step, not as a schedule for when the equipment will be ready for use.
Can I assume a leased terminal works with my payment processor?
No. Don’t assume every terminal works with every processor, or that leasing changes processor requirements. Compare the equipment identified in the proposal with the device requirements documented for your payment-processing arrangement. Check that the specific terminal model under consideration matches the relevant requirements rather than relying on a general description such as “credit-card terminal.” Processor obligations remain separate from ELG’s equipment-leasing role.
Article by
Robert Ensminger
Robert Ensminger is the founder and CEO of Executech Lease Group (ELG Leasing), which specializes in equipment leasing and financing solutions for the merchant-services, payments, POS, and FinTech industries. With more than 20 years of industry experience, Robert helps independent sales organizations, payment processors, POS providers, and software companies develop practical leasing, subscription, and SaaS-monetization programs. He founded ELG in 2010 and guided the company to recognition on the Inc. 5000. His work focuses on responsive service, transparent program structures, and helping ELG’s partners close more business while creating sustainable revenue.