Approximately 78% of U.S. businesses utilize financing to acquire capital assets rather than paying 100% upfront cash, according to the Equipment Leasing and Finance Association. In a market defined by rapid innovation, tying up liquidity in depreciating assets is a strategic error. You need a smarter approach to point of sale hardware financing to stay competitive. High upfront costs for premium systems like Clover shouldn’t stall your operations or drain your reserves. We prioritize professional transparency and results.
You recognize the frustration of managing hardware that becomes obsolete before the warranty expires. It’s a common hurdle for merchants and ISOs who value modern efficiency. This 2026 guide provides the roadmap to master these financial complexities, protect your cash flow, and scale your technology stack without massive upfront capital. We examine 12 to 60 month terms, FMV structures, and the shift toward bundling cloud SaaS fees into one predictable monthly payment.
Key Takeaways
- Preserve working capital by transitioning from high upfront costs to predictable monthly payments for essential business technology.
- Evaluate the strategic advantages of FMV versus Lease-to-Own structures to find the right 12 to 60-month term for your specific refresh cycle.
- Master the process of bundling hardware and cloud-based SaaS subscriptions into a single, efficient point of sale hardware financing agreement.
- Identify how ISOs can use flexible leasing options to overcome price objections and monetize equipment upfront while protecting long-term residuals.
- Streamline your acquisition process by partnering with a selective, results-driven expert that understands the intersection of finance and modern payment tech.
Overcoming the Upfront Capital Hurdle in POS Acquisition
Owning hardware outright is a legacy mindset. It locks your capital in assets that start depreciating the moment you unbox them. For any growing business, liquidity is the lifeblood of survival. Using point of sale hardware financing allows you to treat technology as a strategic asset rather than a massive capital drain. This shift is vital. You aren’t just buying a machine; you’re investing in a revenue engine that powers your entire operation. The true cost of ownership includes more than the sticker price. It involves maintenance, the risk of technical obsolescence, and the hidden cost of downtime when old machines fail.
Modern point of sale systems are no longer just cash registers. They function as sophisticated data hubs that manage inventory, labor, and customer loyalty. When you finance this equipment, you avoid the trap of falling behind. Technology moves fast. Financing ensures you can refresh your stack before your competitors do. We act as a modern facilitator, making this complex process feel organized and predictable. You gain access to premium tools while keeping your cash reserves intact.
To better understand how to evaluate these technology investments, watch this expert breakdown:
The Problem with Outdated Payment Tech
Legacy terminals are a liability. They often lack the advanced security protocols required to protect sensitive data in 2026. Slow checkout speeds don’t just frustrate customers; they actively destroy retention. If your system can’t integrate with modern cloud software, you’re at a competitive disadvantage. You lose the ability to automate reporting or sync with your digital storefront. Financing removes the cost barrier to these essential upgrades, ensuring you always have the latest security and speed.
Preserving Cash Flow for Operations
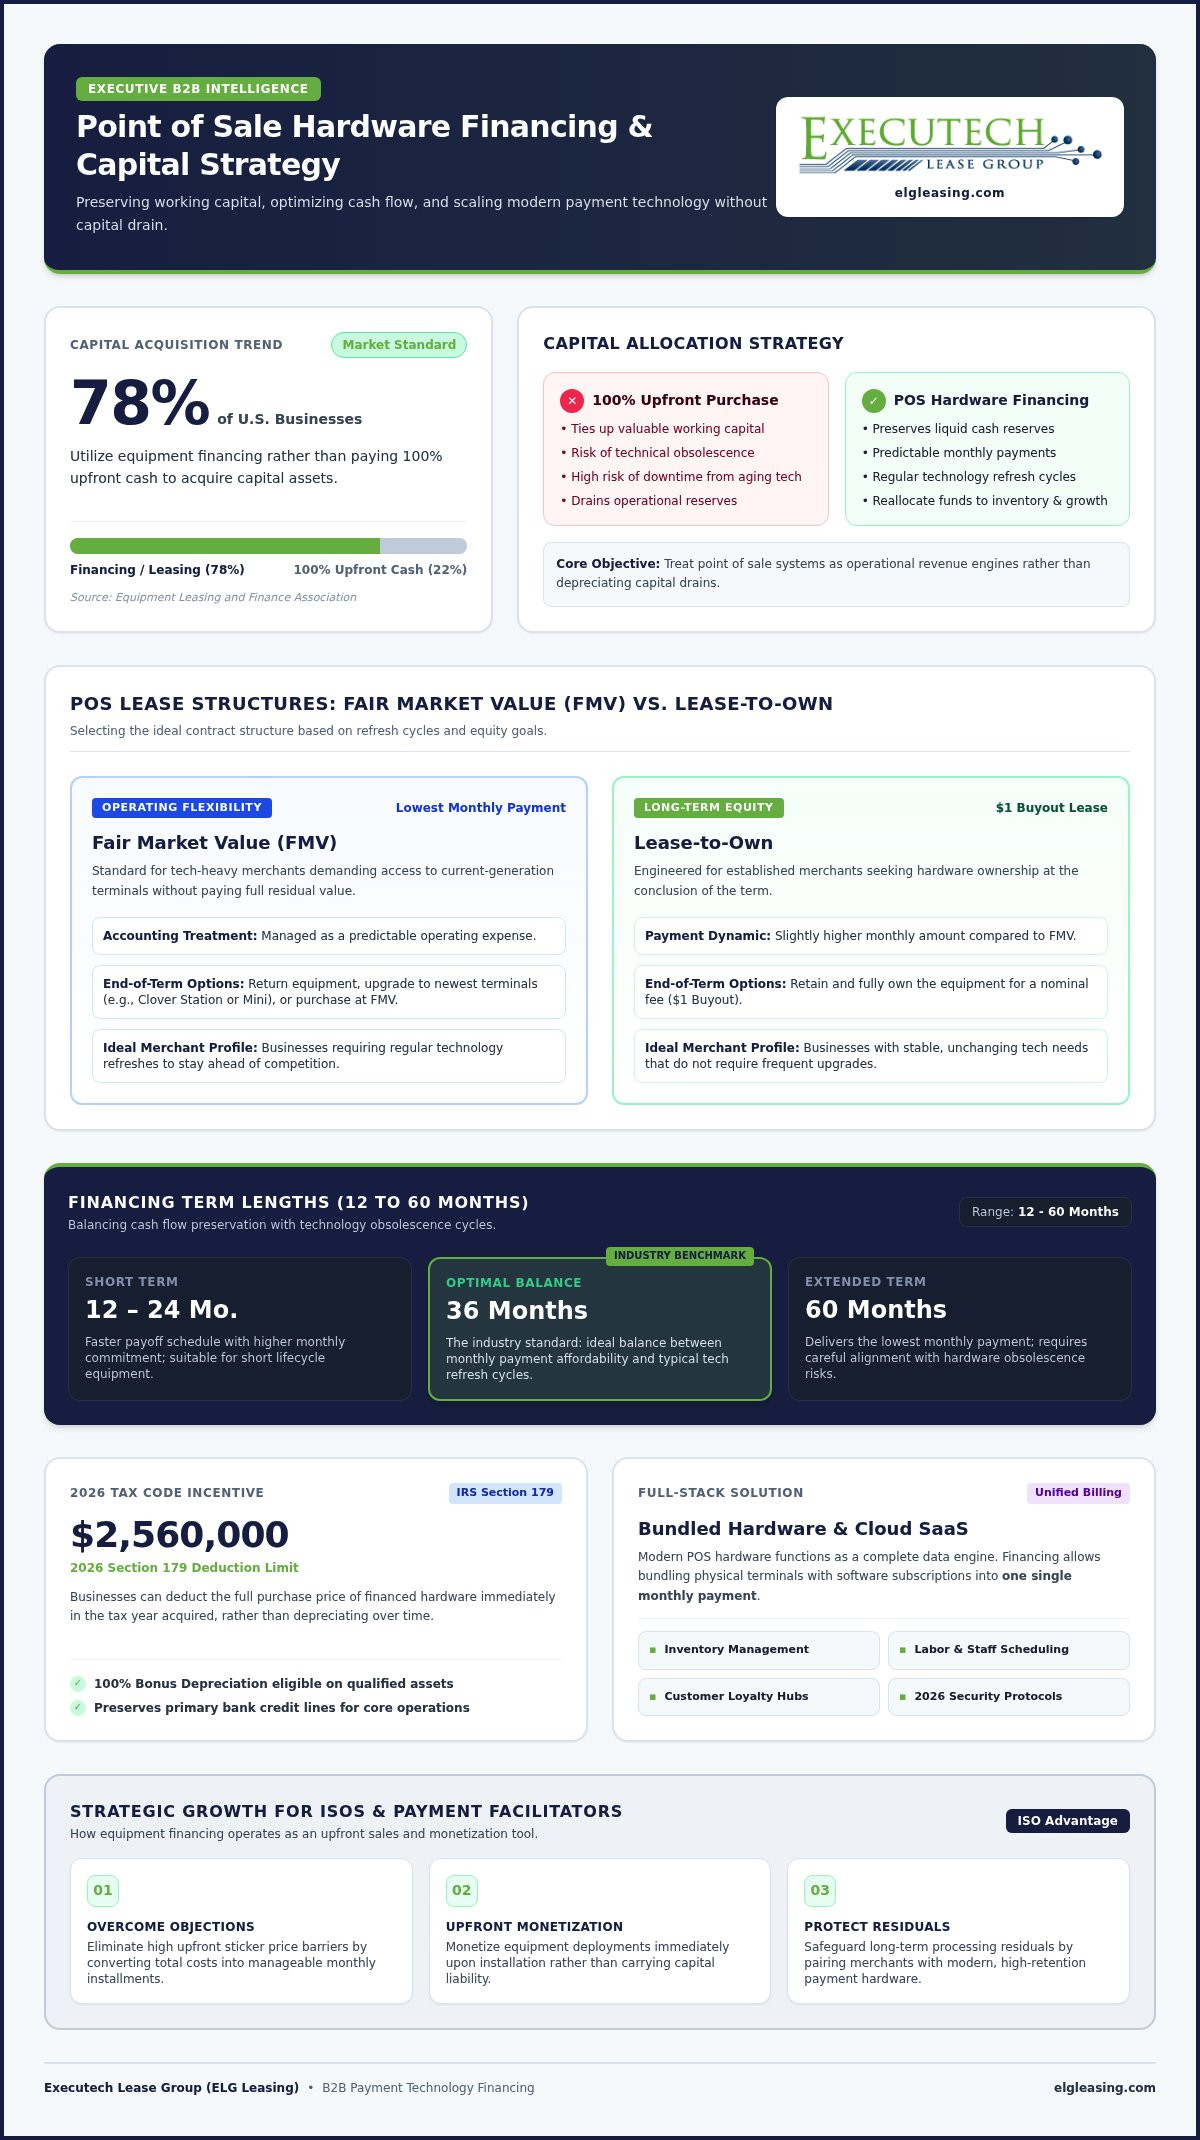
Cash is your most versatile tool. Don’t tie it up in hardware that loses value every day. By leveraging point of sale hardware financing, you reallocate those funds toward inventory or high-impact marketing. The financial benefits are clear. For the 2026 tax year, the Section 179 deduction limit is $2,560,000. This allows you to deduct the full cost of financed equipment immediately. When you combine this with 100% bonus depreciation, the tax savings are substantial. You keep your primary credit lines open for emergencies while building a modern, efficient business.
Decoding POS Lease Structures: FMV vs. Lease-to-Own
Choosing the right agreement structure is just as critical as selecting the hardware itself. You have options ranging from 12 to 60 months. While a 60-month term offers the lowest monthly payment, the 36-month lease is the industry benchmark. It balances affordability with the typical technology refresh cycle. You don’t want to be paying for a terminal that is five years out of date. This is why point of sale hardware financing requires a strategic approach to term length. Following SBA equipment acquisition guidance helps you determine if the preservation of cash flow outweighs the long-term cost of interest.
When to Choose Fair Market Value (FMV)
Fair Market Value leases are the standard for tech-heavy operations. These agreements prioritize accessibility and flexibility. You get the lowest possible monthly payment because you aren’t paying for the full residual value of the machine. At the end of the term, you can return the equipment, upgrade to the latest Clover Station or Mini, or purchase it at its current market value. It’s the ideal choice for businesses that demand premium, current-generation technology to maintain a competitive edge. This model simplifies point of sale hardware financing by treating equipment as a manageable operating expense.
The Case for Lease-to-Own
Lease-to-Own programs, often called $1 Buyout leases, are designed for businesses building long-term equity. You pay a slightly higher monthly amount, but at the end of the term, you own the equipment for a nominal fee. This structure is best for established merchants with stable technology needs who don’t plan on refreshing their hardware every three years. It provides the predictability of a fixed term with the ultimate benefit of full asset ownership. It’s a straightforward path to securing your infrastructure without a large initial capital outlay.
The choice depends on your growth trajectory and accounting preferences. Under ASC 842 standards, FMV leases are typically treated as operating expenses, which helps maintain straight-line P&L treatment. Lease-to-Own contracts are classified as finance leases, allowing you to claim immediate depreciation benefits. Both paths accelerate your access to modern tools without the friction of a traditional bank loan. If you’re ready to secure your equipment, you can start the approval process today to see which structure fits your business model.
Financing the Full Stack: Hardware, Cloud SaaS, and Subscriptions
Modern point of sale systems are useless without the cloud. A Clover Station Duo is just a screen until the SaaS license activates. This reality creates a financial gap for many merchants. Most traditional lenders only want to finance tangible assets. They view software as a “soft cost” with zero recovery value. This outdated logic forces you to pay for years of software licenses upfront or manage fragmented monthly bills. Effective point of sale hardware financing in 2026 must cover the entire stack. We streamline this by bundling your hardware, cloud software, and even installation into one predictable monthly invoice.
This approach protects your liquidity. It also ensures your technology stays synchronized. When you use a fair market value lease to acquire hardware, adding the software component creates a true “as-a-service” experience. You pay for the utility of the system, not just the metal and plastic. Modern specialized POS leasing models now permit up to 100% financing of bundled soft costs, including proprietary configuration and staff onboarding. You get a turnkey solution without the capital disposal loss.
Financing Cloud-Based POS Software
Traditional banks often reject financing for intangible goods like software. We don’t. We recognize that your SaaS subscription is the engine of your business. Our programs allow you to monetize the entire solution. This includes the initial licensing fees, recurring cloud subscriptions, and ongoing support. By integrating these costs into your lease agreement, you avoid the friction of multiple vendors. Everything is consolidated. You can learn more about our SaaS programs to see how we handle these complex bundles. This level of integration is essential for modern retail and hospitality environments where software updates are constant.
Subscription-Based Equipment Models
The industry is shifting toward “Hardware as a Service” (HaaS). This trend is dominating the 2026 payment landscape. It’s about scalability. If you’re opening five new locations, you don’t want five separate hardware bills and five software invoices. You want a single subscription that covers it all. For merchant service providers and ISOs, this model is a powerful tool. It allows you to offer a complete solution to your clients. You provide the premium Clover devices and the necessary software under one umbrella. This reduces merchant sticker shock. It also creates a more stable recurring revenue stream for your portfolio. We facilitate these arrangements with professional transparency and streamlined efficiency. You get the technology you need today without the fragmented financial headaches of the past.
Strategic Growth for ISOs: Financing as a Sales Tool
High-performing Independent Sales Organizations (ISOs) don’t treat equipment as a loss leader. They use point of sale hardware financing as a strategic engine to close larger deals and protect their margins. When a merchant balks at the cost of a premium Clover Station Duo, a cash-upfront model often kills the sale. Financing eliminates this friction. It transforms a significant capital hurdle into a predictable operational expense. By offering flexible terms, you move the conversation from “how much does it cost?” to “how quickly can we modernize your business?”
Specialized leasing partners accelerate your sales cycle by providing rapid, automated underwriting. According to the Crestmont Capital 2026 report, specialty equipment finance providers approve 78% to 84% of applications, compared to just 58% at traditional national banks. This higher approval rate is critical for ISOs who need to monetize hardware upfront. You receive your equipment funding quickly, which bolsters your immediate cash flow while you build long-term processing residuals. It’s a dual-revenue strategy that less agile competitors simply can’t match.
Empowering Sales Agents and Processors
Speed is the ultimate sales tool. Our streamlined application process ensures that your agents aren’t bogged down in paperwork. You can explore our programs for ISOs to see how we integrate into your existing workflow. We act as a selective partner, providing the high standards and professional transparency your brand requires. By using our white-label options, you strengthen your identity as a total solutions provider. You aren’t just selling a merchant account; you’re facilitating a complete technology acquisition. This professional directness builds trust and makes the closing process seamless.
Maximizing Merchant Lifetime Value
Merchant churn is the enemy of residual growth. High-stickiness hardware and software bundles create a barrier to exit that simple processing agreements lack. When you position your ISO as a technology consultant, you become indispensable. Offering regular equipment refreshes through point of sale hardware financing keeps your clients on the latest tech, such as the Clover Flex or Mini. This proactive approach prevents technology obsolescence from driving your merchants toward competitors. You secure the relationship for the long term by managing their entire payment infrastructure. It’s about providing a results-driven professional service that prioritizes the merchant’s operational efficiency.
Streamlining Technology Acquisition with ELG Leasing
Executech Lease Group (ELG Leasing) isn’t a generalist lender. We act as a specialized facilitator with over a decade of industry expertise in the payment space. Our approach to point of sale hardware financing is built on professional transparency and streamlined efficiency. We don’t use flowery prose or hidden fees to mask the reality of your agreement. We provide clear, 12 to 60-month lease terms tailored to the specific needs of your business. This no-nonsense quality ensures you know exactly what you’re signing before you deploy a single device. We prioritize clarity over complexity.
Authorized Clover leasing through our programs covers the entire device family, including the Station, Mini, and Flex. Our digital-first application process is designed for maximum speed. We prioritize getting you the technology you need so you can focus on revenue generation. We move away from cumbersome, old-fashioned methods. We opt instead for a well-oiled machine that delivers results. You get the momentum your business requires without the typical administrative lag found in traditional banking environments. We make high-standard financing accessible to those who value quality.
Why National Merchants Trust ELG
We serve merchants, ISOs, and payment processors nationwide with an unwavering commitment to straightforward contracts. Our role is that of a disciplined gatekeeper. We value quality and long-term partnerships over quantity. This air of exclusivity fosters a sense of trust and security for our clients. You gain access to premium support and asset management throughout your lease term. For a deeper look at the industry landscape, read The Comprehensive Guide to POS Equipment Leasing. We ensure your technology acquisition is organized, predictable, and aligned with your operational goals.
Get Started with Your POS Financing
Acquiring new technology shouldn’t be a stress-inducing ordeal. Our process flow is fast-paced and highly structured. It moves quickly from your initial inquiry to equipment deployment. We eliminate the administrative hurdles found in traditional commercial lending. If you’re ready to modernize your payment infrastructure and protect your cash flow, our results-driven professionals are ready to assist. You can Apply Now for POS Financing to begin the underwriting process today. We provide the tools you need with minimal friction.
Accelerate Your Technology Acquisition Strategy
Modern business demands agility. You can’t afford to let legacy equipment or high upfront costs stall your growth. By mastering point of sale hardware financing, you transform a major capital hurdle into a powerful strategic advantage. You’ve learned that choosing between flexible FMV terms and Lease-to-Own equity depends entirely on your specific technology refresh cycle. You also know that financing the “full stack”, which involves bundling premium hardware with essential cloud SaaS subscriptions, is the industry standard for 2026.
As an authorized Clover leasing partner, ELG Leasing provides the specialized support and asset management ISOs and agents need to thrive in a competitive market. We prioritize professional transparency and results-driven efficiency so you can focus on scaling your operations with confidence. Our 12 to 60-month terms are designed to fit your unique business model without the friction of traditional banking. We act as the modern facilitator your business needs to stay ahead of the curve.
Secure your competitive edge and streamline your payment infrastructure with a partner that understands the intersection of finance and modern tech. Success starts with a smarter, more efficient acquisition strategy.
Frequently Asked Questions
What is the difference between leasing and financing POS hardware?
Leasing through ELG provides access to the equipment without a large capital outlay. While traditional financing often results in immediate ownership and debt, our 12 to 60-month leases offer more flexibility. You choose between Fair Market Value structures, which prioritize lower monthly payments, or Lease-to-Own programs that build equity. Both options streamline your acquisition process. They ensure you aren’t tied to a single piece of hardware as technology evolves.
Can I lease Clover terminals like the Station or Flex through ELG?
You can absolutely lease the full Clover ecosystem through our authorized programs. This includes the high-performance Clover Station Duo, the versatile Clover Mini, and the portable Clover Flex. Our point of sale hardware financing simplifies the process of acquiring these premium devices. We handle the underwriting and funding quickly. This allows you to deploy the latest smart terminals without draining your business reserves or relying on traditional bank loans.
Does POS hardware financing include the software and SaaS costs?
Our point of sale hardware financing includes the ability to bundle software and SaaS costs into a single agreement. We recognize that modern hardware requires cloud-based software to function. Unlike traditional lenders who reject “soft costs”, we permit up to 100% financing for SaaS subscriptions and configuration fees. This consolidation results in one predictable monthly invoice. It eliminates the administrative burden of managing multiple vendor payments across your organization.
What happens at the end of a Fair Market Value (FMV) lease?
At the end of a Fair Market Value (FMV) lease, you have three clear options. You can return the equipment to us, upgrade to the latest technology generation, or purchase the hardware at its current market value. This structure is ideal for businesses that prioritize tech refreshes. It prevents the accumulation of obsolete hardware. It also maintains a lower monthly payment compared to full ownership paths, preserving your liquidity for other operational needs.
Are there tax benefits to leasing point of sale equipment?
Leasing offers significant tax advantages under current 2026 regulations. For Lease-to-Own programs, the Section 179 deduction limit is $2,560,000, allowing for full immediate expensing. FMV leases are typically treated as operating expenses, providing straight-line P&L treatment. These structures help you monetize your investment while adhering to ASC 842 accounting standards. Always consult with your tax professional to confirm how these specific benefits apply to your business’s financial situation.
How long are the typical lease terms for credit card machines?
Typical lease terms for credit card machines and POS systems range from 12 to 60 months. We find that the 36-month term is the industry benchmark for most merchants. It offers a balance between affordable monthly payments and the natural three-year technology refresh cycle. Shorter terms are available for those who want to own their assets faster. Longer terms prioritize maximum cash flow preservation for larger multi-station deployments.
Can ISOs and sales agents offer their own branded leasing programs?
ISOs and sales agents can leverage our white-label leasing options to strengthen their own brands. We act as a selective partner, providing the back-end infrastructure and underwriting expertise you need to succeed. This allows you to offer comprehensive equipment solutions under your own banner. You can monetize hardware upfront and protect your processing residuals. It positions your organization as a total technology consultant rather than just another payment processor.
Is it possible to upgrade my hardware before the lease term ends?
Upgrading your hardware before the lease term ends is possible through our flexible technology refresh programs. We understand that your business needs may change or that a superior device might hit the market. We work with you to restructure your agreement to include the new equipment. This ensures you always have access to the latest tools without being stuck in an obsolete contract. It’s part of our commitment to being a modern facilitator.
Article by
Robert Ensminger
Robert Ensminger is the founder and CEO of Executech Lease Group (ELG Leasing), which specializes in equipment leasing and financing solutions for the merchant-services, payments, POS, and FinTech industries. With more than 20 years of industry experience, Robert helps independent sales organizations, payment processors, POS providers, and software companies develop practical leasing, subscription, and SaaS-monetization programs. He founded ELG in 2010 and guided the company to recognition on the Inc. 5000. His work focuses on responsive service, transparent program structures, and helping ELG’s partners close more business while creating sustainable revenue.