No money down doesn’t mean no ongoing payments. The right structure still depends on the payment equipment you need, your business plans, and what you want at the end of the term. Customizable equipment lease plans from Executech Lease Group (ELG Leasing) give you clear choices to compare, without treating every business or purchase the same.
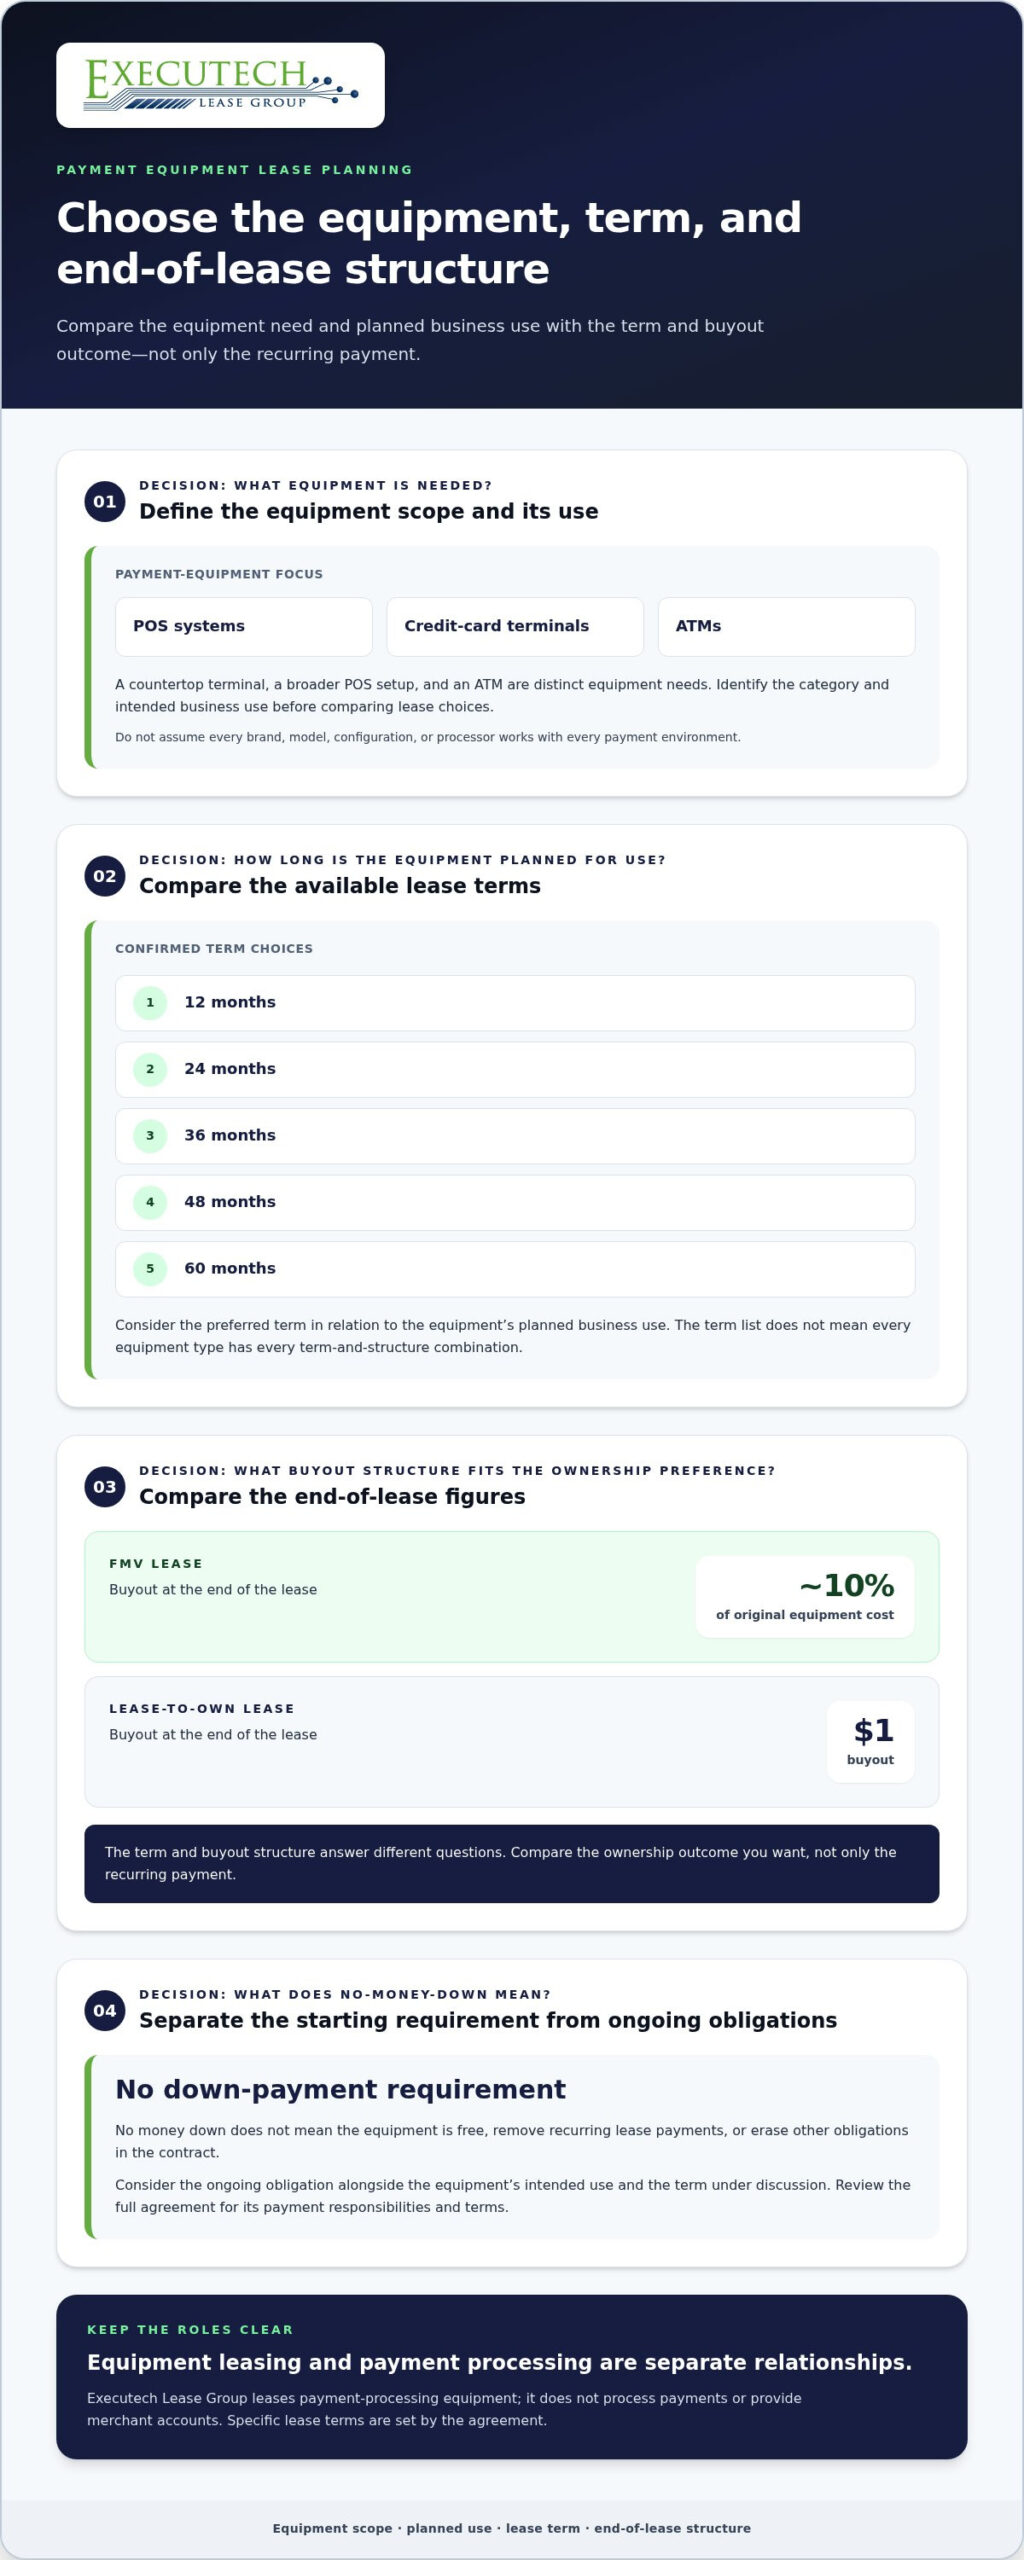
It’s reasonable to focus on the monthly obligation, but the term and end-of-lease option matter too. ELG offers confirmed terms of 12, 24, 36, 48, and 60 months, along with two distinct buyout structures: an FMV lease ends with a buyout of about 10% of the original equipment cost, while a lease-to-own lease ends with a $1 buyout. These options serve different ownership preferences, so it’s important to understand the distinction before choosing.
This guide explains how to match equipment, term, and end-of-term structure to your business situation. You’ll also see which questions merchants, vendors, ISOs, and other payments professionals should resolve before moving forward with payment equipment leasing.
Key Takeaways
- Customizable equipment lease plans align the payment technology, business use, term, and end-of-lease preference.
- Compare FMV and lease-to-own structures by the ownership outcome you want, not just the recurring payment.
- Prepare for a lease discussion by identifying the equipment, how you’ll use it, your term preference, and your buyout questions.
- Keep equipment leasing distinct from payment processing, which remains a separate business relationship.
What Makes an Equipment Lease Plan Customizable for Payment Technology?
Customizable equipment lease plans align the payment equipment, lease term, lease structure, and intended business use. Customization concerns how those elements fit together, not a promise of approval, savings, or a particular business outcome.
A merchant equipping a location has different priorities from a vendor arranging equipment for a customer. Start by defining the equipment and how it will be used, then compare lease choices against that need. Keep the roles clear, too: a business using payment technology, a party arranging equipment, and a party handling payment processing may each have a different place in the transaction.
Which payment equipment can a lease plan cover?
ELG’s payment-equipment focus includes POS systems, credit-card terminals, and ATMs. These categories serve different operational purposes, so define the equipment scope before comparing lease structures. A countertop terminal, a broader POS setup, and an ATM are distinct equipment needs.
Be specific about the equipment category and intended use. Don’t assume every brand, model, configuration, or processor works with every payment environment. A clear scope gives the lease discussion a practical starting point without treating compatibility as universal.
Who uses customizable payment-equipment lease plans?
Different participants approach equipment leasing from different sides of the payments ecosystem:
- Merchants may use no-money-down leasing to access payment equipment without a down-payment requirement. That doesn’t mean the equipment is free or that recurring lease obligations disappear.
- ISOs and independent sales agents may discuss equipment leasing in connection with the merchants and payment-technology opportunities they serve. Their role is distinct from the lease itself.
- Vendors and POS dealers may explore how equipment leasing fits into offering payment hardware to business customers. The equipment arrangement remains separate from processing services.
- ISVs have a separate conversation about SaaS program interest. That topic concerns software, not the equipment lease terms discussed here, and shouldn’t be treated as a confirmed funding outcome.
These distinctions keep responsibilities clear. A merchant’s equipment need, a dealer’s sales process, and an ISV’s software interests are related to payment technology, but they aren’t the same lease discussion. ELG leases payment-processing equipment; it doesn’t process payments or provide merchant accounts.
Once you’ve identified the equipment and your role in the transaction, you can consider the lease term and end-of-lease structure in context. That creates a focused discussion based on the payment technology involved, rather than assumptions about what a plan will deliver.
Which Lease Plan Details Can You Align Before Proceeding?
Once you’ve identified the payment equipment and its use, the next step is to compare the lease term and structure. These details shape the agreement, but they don’t guarantee approval, a particular payment, or a specific financial result. Customizable equipment lease plans start with choices you can define clearly before moving into the full discussion.
How should you think about equipment and term?
Begin with the equipment involved and the business purpose it will serve. A POS system, credit-card terminal, or ATM may call for a different conversation, so keep the equipment scope clear rather than assuming all combinations have identical terms.
ELG’s confirmed equipment lease term choices are:
- 12 months
- 24 months
- 36 months
- 48 months
- 60 months
Think about your preferred term in relation to the equipment’s planned business use. Then compare the available lease structure separately. ELG’s equipment lease program structures provide context for that comparison. The term list doesn’t mean every equipment type has every term-and-structure combination.
Industry resources can add general context, too. The Equipment Leasing and Finance Association offers information about equipment finance, while the terms of a specific lease are set by its agreement. Use industry material for background, not as a substitute for understanding the details of your own arrangement.
What does no-money-down mean in practice?
No-money-down addresses one point: the lease has no down-payment requirement. It doesn’t mean the equipment is free, remove recurring lease payments, or erase other obligations in the contract. Read the full agreement so you understand the payment responsibilities and terms, not just the amount due at the start.
Keep the language precise. No down payment is not the same as no financial commitment, and it doesn’t guarantee a particular outcome. For budgeting, consider the ongoing obligation alongside the equipment’s intended use and the term under discussion.
Equipment lease terms also stand apart from hardware subscription and SaaS program discussions. Don’t treat those subjects as extra lease terms or assume a subscription or SaaS program is currently available. Keep the equipment agreement focused on the equipment, its lease term, and the structure being considered.
Before taking the next step, write down the equipment category, its intended use, your preferred term, and any questions about the agreement. That gives the discussion a clear starting point. When you’re ready to proceed, ELG’s payment-equipment lease application is the relevant next step.
FMV or Lease-to-Own: Comparing End-of-Lease Options
The buyout structure answers a different question from the lease term: what figure applies at the end of the agreement if you choose to buy the equipment? ELG offers two distinct equipment lease structures. Compare their stated buyouts directly, then consider which end-of-lease purchase option better fits your plans for the payment equipment.
| Lease structure | Confirmed end-of-lease buyout | Decision question |
|---|---|---|
| FMV equipment lease | About 10% of the original equipment cost | Does this end-of-lease buyout align with your purchase preference? |
| Lease-to-own equipment lease | $1 | Does this stated buyout fit your intention to own the equipment? |
The FMV figure of about 10% and the lease-to-own figure of $1 are end-of-lease buyouts, not monthly payments or the total equipment price. Keep those amounts in their proper context when comparing options. They don’t describe the recurring payments during the lease, and they shouldn’t be read as the full price of the equipment.
What does the FMV equipment lease end with?
An FMV equipment lease ends with a buyout of about 10% of the original equipment cost. That figure applies to the end-of-lease buyout only. It isn’t a monthly payment, and it doesn’t establish a calculation formula or describe other contract terms. Review the agreement’s stated details so you understand how this structure applies to your equipment.
How does lease-to-own differ?
A lease-to-own equipment lease ends with a $1 buyout. This figure belongs specifically to the lease-to-own structure; it isn’t the FMV buyout or a monthly payment. Compare it with the FMV option by focusing on the two stated end-of-lease figures and the ownership preference behind your choice, rather than assuming one structure is always cheaper or better.
Use the comparison to clarify your priorities before discussing a plan. For example, if your main question is the end-of-lease purchase figure, identify which stated buyout aligns with your preference. If you’re focused on recurring payments, keep that question separate and review the payment terms in the agreement. The buyout figures alone don’t tell you the monthly payment or total cost.
Customizable equipment lease plans let you compare structure against your business use and end-of-lease preference. Before proceeding, make sure you can distinguish the FMV buyout from the lease-to-own buyout, and avoid treating either figure as a complete summary of the agreement. The contract terms provide the specific details for the lease you’re considering.
How to Prepare for a Custom Equipment Lease Discussion
A focused conversation starts with clear priorities, not assumptions about approval, timing, or what a lease includes. Before discussing a payment-equipment lease, organize the details you already know and separate open questions from confirmed choices. That makes it easier to compare structures and understand the agreement being considered.
What should you define before discussing a plan?
Prepare these points in sequence. Keep each one specific to the equipment and business use involved:
- Identify the equipment. Name the POS system, credit-card terminal, or ATM you’re discussing. Be precise about the equipment scope without assuming compatibility across brands, models, or processors.
- Describe the intended use. Explain how the equipment fits into your business operations. This gives the discussion useful context without assuming a particular business result.
- Set a term preference. Note which available lease term you’d like to discuss. Treat term preference as one part of the structure, not as a guarantee that every equipment-and-term combination is available.
- Prepare buyout questions. Decide whether you want to compare the FMV and lease-to-own end-of-term options. Ask about any contract detail that a general program description doesn’t explain, including how the specific agreement states its obligations.
This preparation is about clarifying the conversation. It isn’t a list of required documents or eligibility criteria. For a high-level view of how the stages fit together, review ELG’s equipment lease process flow. Use it as process context, while relying on the agreement for the terms that apply to your lease.
What happens after a credit decision?
Our goal is to deliver credit decisions in under 2 business hours. That goal applies to the credit-decision stage only. It doesn’t establish when funding, vendor payout, delivery, or installation will happen. Those are separate steps, and no timing for them is stated here.
Keep the stages distinct. A credit decision is not a promise of funding or a guarantee of a particular result, and it doesn’t determine deployment timing. If you’re discussing next steps, frame them as questions about the transaction rather than assuming one stage automatically triggers another. This keeps expectations grounded in what’s known.
Customizable equipment lease plans are easier to discuss when the equipment, purpose, preferred term, and end-of-term questions are organized in advance. Bring that outline into the conversation, then use the agreement to understand the details that apply to your specific arrangement.
How Executech Lease Group (ELG Leasing) Fits a Custom Payment-Equipment Plan
ELG is an equipment lease brokerage focused on payment technology. Its equipment plans are built around POS systems, credit-card terminals, and ATMs, with choices that let you consider both the lease term and the end-of-lease structure. The confirmed term options are 12, 24, 36, 48, and 60 months. FMV and lease-to-own structures also have distinct end-of-term buyouts, so compare the agreement details with your equipment needs and ownership preference.
Those are equipment lease arrangements, not payment processing services. ELG handles equipment leasing; a merchant’s processing relationship, merchant account, and processor obligations remain separate. Keeping the responsibilities clear helps merchants, vendors, and other payments professionals understand what the lease covers and what belongs elsewhere.
What does ELG handle, and what stays separate?
ELG focuses on leasing payment-processing equipment. It doesn’t provide payment processing, merchant accounts, installation, or equipment service. ELG also doesn’t provide equipment warranties, maintenance, repairs, or replacements. Any equipment warranty comes only from the equipment manufacturer, so warranty questions belong with that manufacturer.
For merchants, the lease discussion concerns the equipment and its agreement. For vendors, ISOs, independent sales agents, and POS dealers, it concerns how equipment leasing relates to their role in the payments ecosystem. These roles may intersect around a transaction, but leasing and processing remain distinct.
How can a payment-industry partner start the conversation?
Vendors, ISOs, and MSPs can use the Become a Vendor form to make an inquiry about a leasing partnership. It’s a contact inquiry, not a financing application or credit decision. Share the context of your business and the equipment conversations you’re exploring; don’t treat an inquiry as a promise of approval, funding, or a specific outcome.
ISVs have a separate path for discussing SaaS program fit. That conversation concerns software, not the equipment lease terms or buyout figures, and it doesn’t promise that funding is currently available. Keeping those topics separate makes it easier to frame the right discussion without assuming a program result.
For merchants, the practical starting point is the equipment, intended use, preferred term, and end-of-lease preference. For industry partners, begin with your role and the payment-equipment opportunity you want to discuss. In either case, review the agreement for the terms that apply to the specific arrangement. Customizable equipment lease plans help organize these choices, but they don’t guarantee a particular financial or operational outcome.
Move Forward with a Clear Equipment Plan
Your next step is to turn your equipment priorities into a focused conversation. Bring the intended use, preferred structure, and any unresolved contract questions together. That gives you a practical basis for discussing how Customizable equipment lease plans may fit your payment-technology needs, without confusing equipment leasing with payment processing.
A clear starting point makes it easier to evaluate the arrangement on its own terms. Keep your business goals in view, review the agreement carefully, and make decisions based on the responsibilities and options it actually sets out.
With the right questions in hand, you can take the next step with greater clarity and confidence.
Frequently Asked Questions
Does ELG require money down?
No, ELG offers equipment leasing with no down-payment requirement. That addresses the amount due as a down payment, not the full financial commitment. For example, when planning a purchase, distinguish any initial down payment from the recurring payments and other obligations stated in the lease. Review the proposed agreement’s payment schedule and terms before proceeding so your budget reflects the actual arrangement.
How fast does ELG make a decision?
Our goal is to deliver credit decisions in under 2 business hours. That goal refers only to the credit decision, not to later transaction stages. It doesn’t establish when funding, a vendor payout, equipment delivery, or installation will occur. If you’re coordinating equipment for a business opening or technology change, plan those steps separately rather than treating the decision window as a delivery schedule.
How do the two buyouts differ?
The FMV equipment lease ends with a buyout of about 10% of the original equipment cost; the lease-to-own equipment lease ends with a $1 buyout. Each figure applies only to its named structure and describes an end-of-lease buyout, not a monthly payment or total equipment price. Use the distinction to frame your ownership preference, then review the specific agreement for its terms.
Can I choose a lease term that fits my equipment plan?
ELG’s equipment lease term choices are 12, 24, 36, 48, and 60 months. Customizable equipment lease plans involve aligning the equipment, intended business use, and structure with a term under discussion. Don’t assume each equipment type can be paired with every structure and term. For a specific proposal, use the written agreement to identify the term and conditions that apply to that arrangement.
Does ELG process payments?
No, ELG leases equipment and does not process payments. Your payment processor relationship remains separate from the equipment lease. For instance, a lease doesn’t establish transaction pricing, supply a merchant account, or change obligations you have through a processor. Keep questions about equipment financing and payment acceptance in their respective conversations, and review each agreement for the responsibilities it covers.
Can an ISV discuss SaaS funding with ELG now?
Yes, ELG invites ISVs to discuss their software business and potential fit with its SaaS funding program. ELG is actively staging ISVs for the program, but an invitation to engage isn’t a promise that funding is currently available or will follow. Keep this conversation separate from payment-equipment leasing: equipment lease terms and buyout figures don’t apply to SaaS.
Does ELG provide equipment warranties or repairs?
No, ELG doesn’t provide equipment warranties, maintenance, repairs, or replacements. Any equipment warranty comes only from the equipment manufacturer. If warranty coverage matters to your purchase decision, review the manufacturer’s information for the specific equipment you’re considering. Keep that coverage separate from the lease agreement, which addresses the equipment-leasing arrangement rather than service or repair coverage.
Article by
Robert Ensminger
Robert Ensminger is the founder and CEO of Executech Lease Group (ELG Leasing), which specializes in equipment leasing and financing solutions for the merchant-services, payments, POS, and FinTech industries. Robert helps ISOs, payment processors, POS providers, and software companies build practical equipment leasing programs. He founded ELG in 2010. His work focuses on responsive service, transparent program structures, SaaS-monetization programs, and helping ELG’s partners close more business while creating sustainable revenue.